Mr. Rahman in this LinkedIn post offers some well-known ways for financial institutions to manage risk and protect their valuable clients and members from being defrauded. It is well done and a good review for anyone working in a financial institution that has responsibility to protect their customers.
Mostafizur Rahman, MBA, AIBB, JAIBB, BSc (EEE)
Banking Operations Professional | Cards & Digital Banking Operations | Process Optimization | Operational Excellence | AML & Compliance Enthusiast | CAMS Aspirant | JAIBB | AIBB
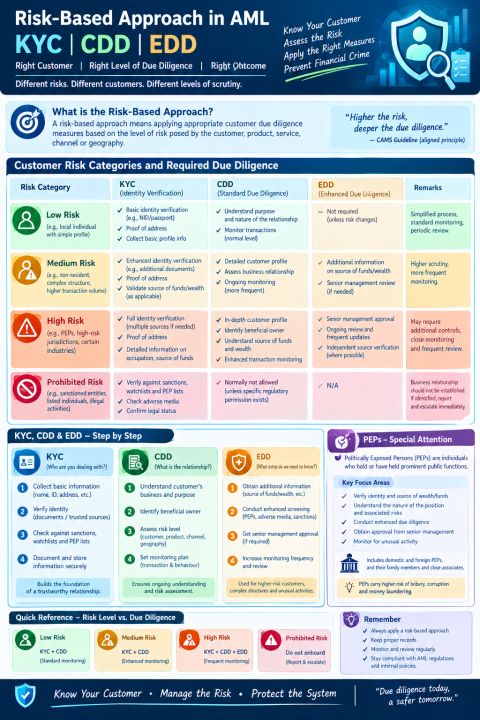
Risk-Based AML: KYC, CDD & EDD
Not every customer presents the same level of financial crime risk — and therefore, not every customer should receive the same level of scrutiny.
A risk-based AML framework helps institutions apply the right level of due diligence according to the customer’s risk profile, products, services, channels and geographic exposure.
🔹 KYC — Know Your Customer
The foundation of the relationship.
• Collect and verify customer identity
• Obtain basic customer information
• Understand the purpose and intended nature of the relationship
• Screen against relevant sanctions, PEP and watchlists
• Maintain appropriate records
🔹 CDD — Customer Due Diligence
Go beyond identity and understand the relationship.
• Understand the customer’s business and activities
• Identify and verify beneficial ownership
• Assess the customer’s risk profile
• Understand source of funds/wealth where appropriate
• Conduct ongoing monitoring and keep information up to date
🔹 EDD — Enhanced Due Diligence
For higher-risk relationships, deeper scrutiny is required.
• Obtain additional information
• Establish source of funds and/or source of wealth
• Conduct enhanced screening and investigation
• Obtain senior management approval where required
• Apply enhanced ongoing monitoring
🔹 Risk-Based Application
🟢 Low Risk → Standard KYC/CDD and normal monitoring
🟡 Medium Risk → More detailed assessment and increased monitoring
🔴 High Risk → Enhanced due diligence, deeper verification and closer monitoring
⛔ Prohibited/Restricted → Do not establish or continue the relationship where prohibited by applicable law, sanctions or internal policy; escalate and take required action.
🔹 PEPs — Special Attention
PEP status does not automatically mean that a person is involved in financial crime. However, PEP relationships can present higher corruption and bribery risks and therefore require appropriate enhanced measures.
Key considerations include:
• Identity and PEP status
• Source of wealth and source of funds
• Nature of the public function
• Relevant family members and close associates
• Senior management approval where required
• Enhanced ongoing monitoring
📌 Key Takeaway:
“KYC tells you who the customer is.
CDD helps you understand the relationship.
EDD helps you manage higher risk.
The objective is not simply to collect documents — it is to understand, assess and continuously manage risk.”
#AML #KYC #CDD #EDD #PEP #FinancialCrime #Compliance #RiskBasedApproach #CustomerDueDiligence #AMLCompliance #TransactionMonitoring #MoneyLaundering #Banking