This LinkedIn post is a timely reminder that KYC/AML compliance is ongoing and does not stop once you have onboarded a new client/member. Life changes and new development and events can have implications on what a financial institution customer needs to do (e.g., retirement, divorce).
In doing periodic reviews, the financial institution needs to ensure all information is accurate and up to date with their present circumstances. As stated below, “Effective AML compliance requires ongoing monitoring and periodic reassessment.”
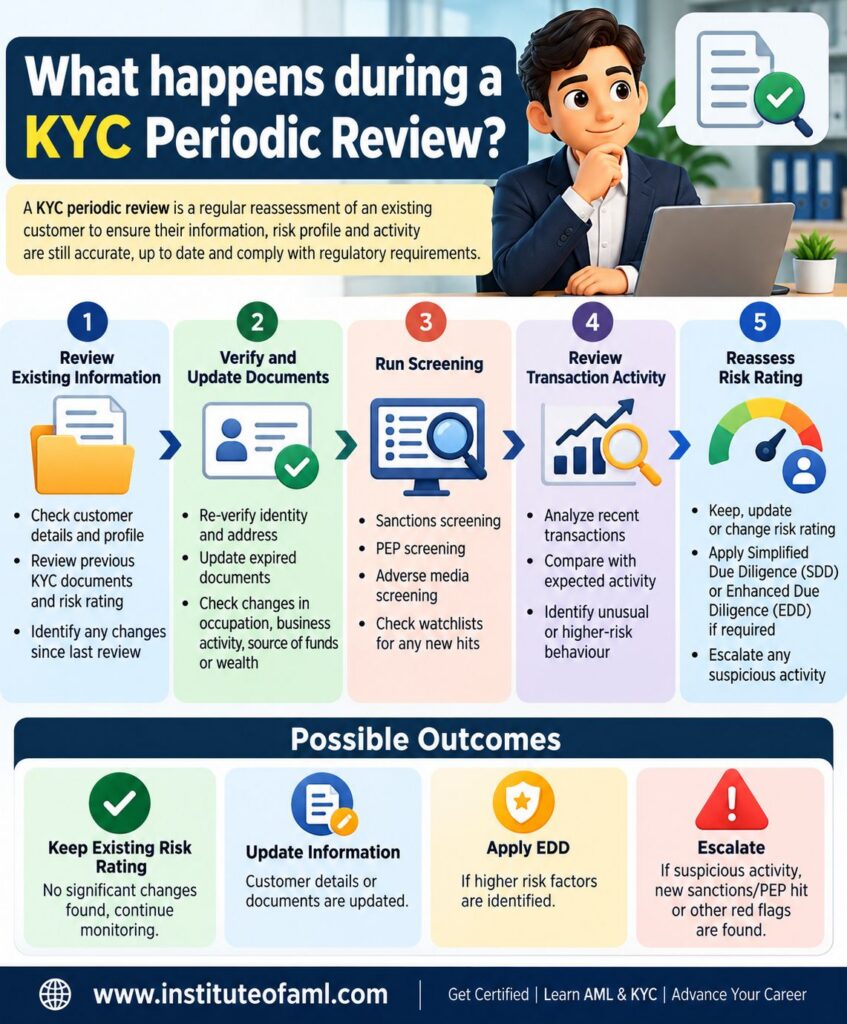
A periodic review is more than just checking documents. It’s about making sure the customer’s identity, risk profile, and activity are still accurate and up to date.
Key steps include: ✅ Review customer information 📄 Verify and update KYC documents 🔎 Perform Sanctions, PEP & Adverse Media screening 💳 Review transaction activity 📊 Reassess the customer risk rating ⚠️ Apply EDD or escalate red flags when required
Remember: KYC is not a one-time process. Effective AML compliance requires ongoing monitoring and periodic reassessment.
Want to strengthen your AML/KYC knowledge and get certified?